
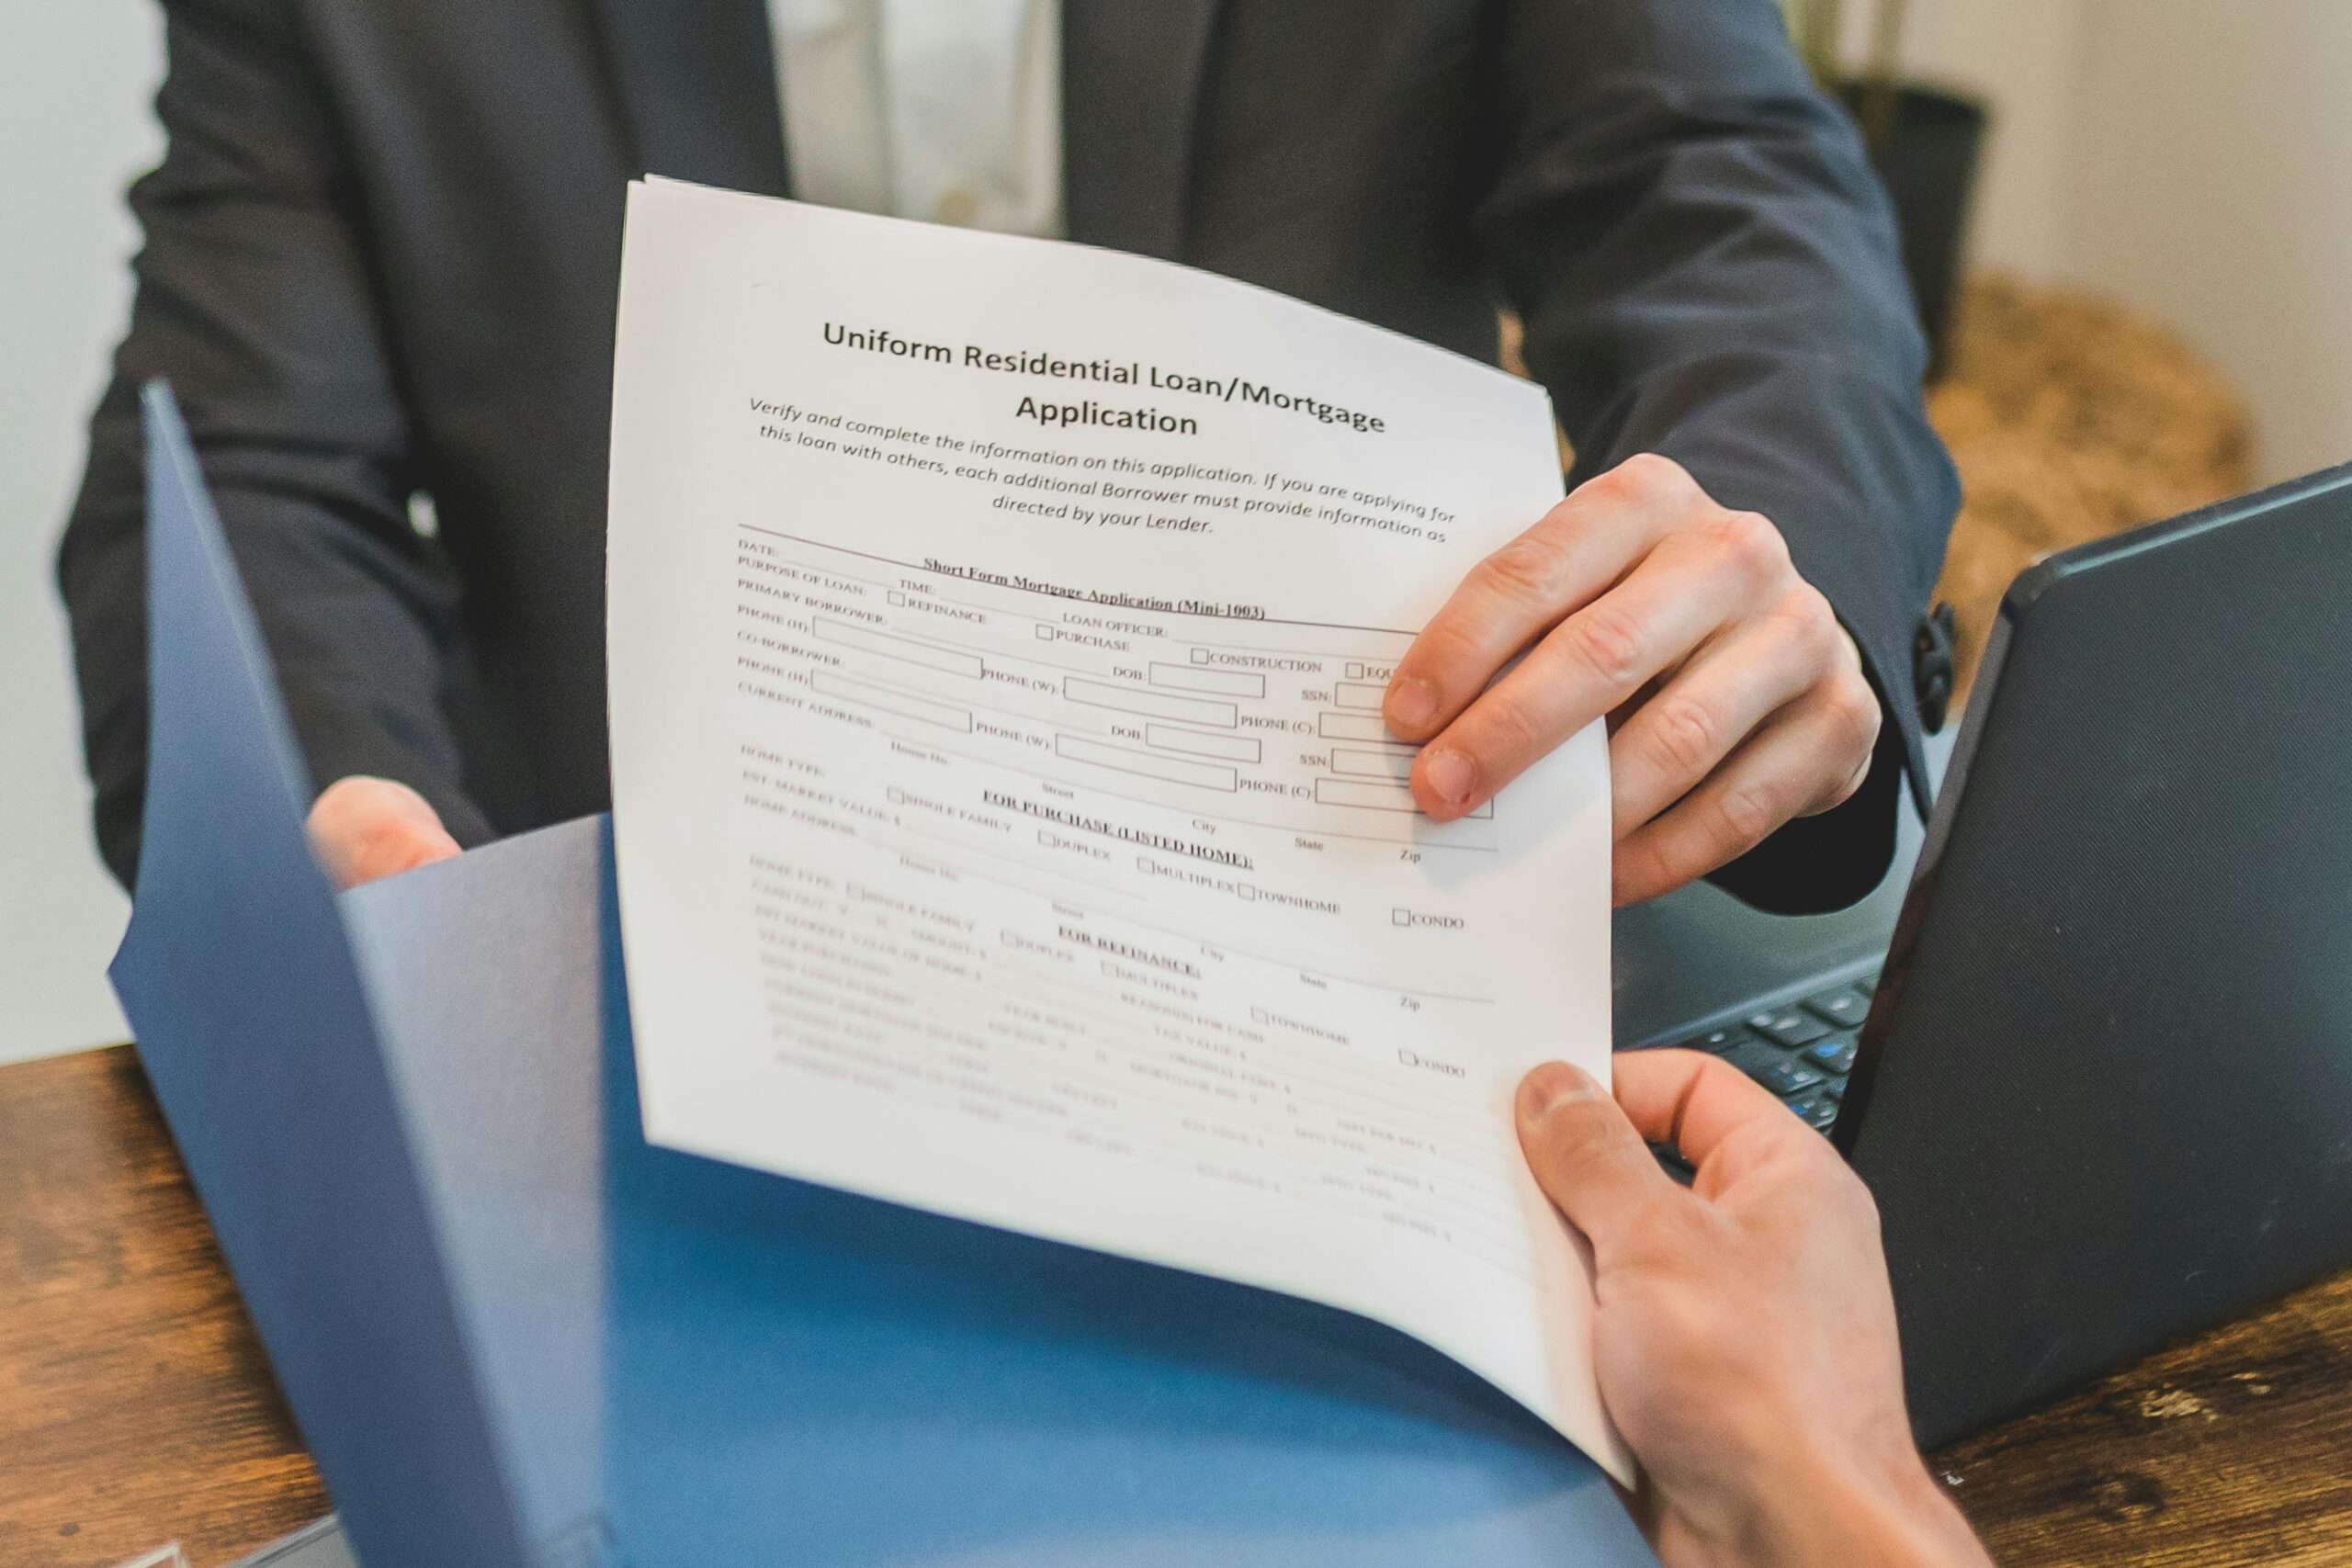
Securing financing for your business is often a critical step toward growth, innovation, or simply maintaining operations. However, with countless applications vying for attention, crafting one that stands out requires strategic planning and attention to detail. This guide provides a comprehensive roadmap to help entrepreneurs develop a financing application that not only gets noticed but also maximizes the chances of approval.
Step 1: Define Your Loan Purpose Clearly
The foundation of any successful financing application is a clear and compelling purpose. Lenders need to understand why you need the funds and how they will be used.
- Be Specific: Outline precise objectives, such as purchasing equipment, expanding inventory, acquiring real estate, or funding marketing initiatives.
- Align with Business Goals: Demonstrate how the loan supports your broader growth strategy. For example, if you’re opening a new location, include projections for increased revenue and market share.
- Calculate Accurately: Avoid requesting arbitrary amounts. Use detailed financial forecasts to justify the loan amount and show lenders you’ve done your homework.
Step 2: Build a Strong Credit Profile
Your creditworthiness plays a pivotal role in determining whether your application gets approved. Both personal and business credit histories are scrutinized by lenders.
- Check Personal Credit Reports: Obtain free annual credit reports from platforms like AnnualCreditReport.com and ensure there are no errors. Correct inaccuracies promptly.
- Establish Business Credit: If your business lacks credit history, register with agencies like Dun & Bradstreet to obtain a D-U-N-S® Number. This allows lenders to assess your business profile independently of personal credit.
- Maintain Timely Payments: A history of on-time payments enhances your credibility and may secure better loan terms.
Step 3: Prepare Comprehensive Financial Documentation
Financial transparency is crucial for gaining lender trust. Your application should include detailed financial statements that highlight your business’s fiscal health.
Key documents to include:
- Profit & Loss Statements: Showcase profitability trends over time.
- Cash Flow Statements: Demonstrate operational efficiency by tracking inflows and outflows.
- Balance Sheets: Provide an overview of assets, liabilities, and equity to indicate financial stability.
- Tax Returns: Supply recent tax filings to confirm compliance and income consistency.
Step 4: Supply Trade References
Trade references are an often-overlooked component that can significantly strengthen your application.
- Choose Reliable Partners: Select suppliers or vendors who can vouch for your payment reliability. Ideally, these references should have long-standing relationships with your business.
- Provide Complete Information: Include the company name, address, contact person, and phone number for each reference. This instills confidence in lenders about your financial management capabilities.
Step 5: Craft a Professional Business Plan
A well-thought-out business plan demonstrates your preparedness and vision for success.
Essential elements of a standout business plan:
- Executive Summary: Offer a concise overview of your company’s mission, products/services, and goals.
- Market Analysis: Highlight industry trends, target audience insights, and competitive positioning.
- Operational Strategy: Detail how you plan to achieve your objectives using the loan funds.
- Financial Projections: Include realistic revenue forecasts supported by data.
Step 6: Research Lenders Thoroughly
Not all lenders are created equal. Researching their requirements and preferences ensures you target the right institutions for your financing needs.
Factors to consider:
- Eligibility Criteria: Understand minimum requirements such as credit scores, revenue thresholds, or collateral needs.
- Loan Terms: Compare interest rates, repayment schedules, and fees across multiple lenders.
- Specialized Programs: Explore options like SBA loans if you meet their criteria. These loans often offer favorable terms but require extensive documentation.
Step 7: Submit an Impeccable Application
When submitting your financing application:
- Ensure all information is accurate and complete.
- Double-check for errors or inconsistencies in financial data.
- Respond promptly to any requests for additional documentation during the review process.
Common Mistakes to Avoid
Even well-prepared applications can falter due to avoidable errors. Here are some pitfalls to watch out for:
1. Lack of Clarity
Vague explanations about fund usage can undermine credibility. Always provide specific details about how the loan will be utilized.
2. Incomplete Documentation
Missing financial statements or trade references can delay processing or lead to outright rejection.
3. Weak Credit History
Neglecting personal or business credit scores reduces approval chances. Address issues proactively before applying.
4. Overestimating Loan Amounts
Requesting more than necessary burdens your business with excessive debt. Calculate needs carefully based on realistic projections.
Best Practices for Success
To make your financing application truly stand out:
- Focus on Professionalism: Present documents neatly and ensure all communication is courteous and timely.
- Leverage Technology: Use online tools or platforms like SBA’s Business Plan Tool for streamlined preparation.
- Seek Expert Advice: Consult mentors or financial advisors who specialize in loan applications.
- Learn from Rejections: If denied, ask lenders for feedback and address shortcomings in future applications.
Real-Life Examples of Success
Many businesses have leveraged loans strategically to achieve remarkable growth:
- Amazon’s Expansion Loan: A $1 billion loan enabled Amazon to scale its distribution network and dominate e-commerce markets globally.
- Tesla’s Innovation Loan: Tesla’s $465 million Department of Energy loan fueled advancements in electric vehicle technology and infrastructure development.
These examples underscore how well-prepared applications can unlock transformative opportunities.
Creating a financing application that stands out requires meticulous preparation, strategic thinking, and attention to detail. By defining your loan purpose clearly, building strong credit profiles, providing comprehensive documentation, and presenting a professional business plan, you can significantly enhance your chances of approval.
With these steps in place, not only will you increase the likelihood of securing funding but also position yourself as a trustworthy borrower ready to achieve long-term success!
Content generated by Perplex.ai